
The picnic is a memory. The close is the sentence.
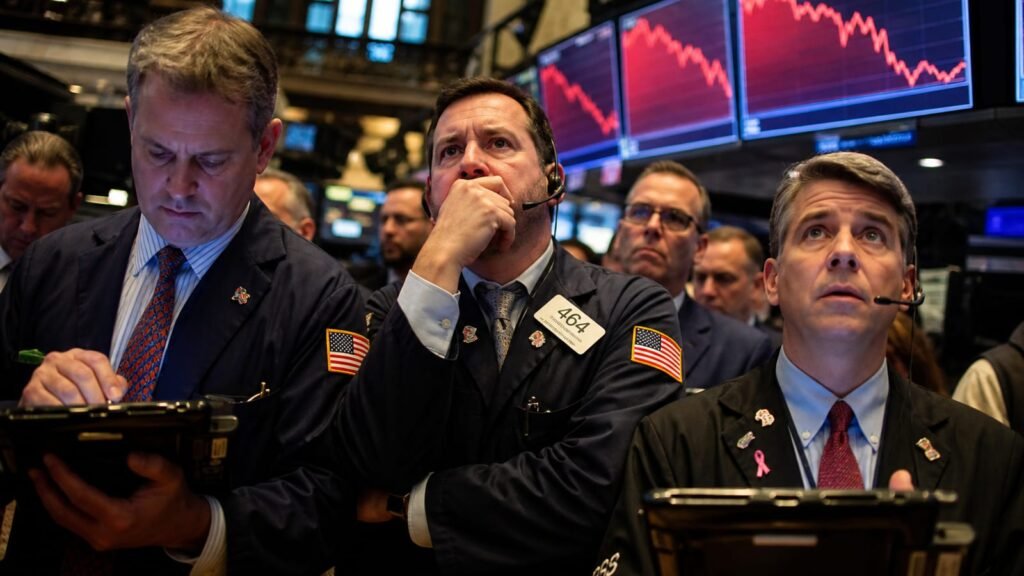
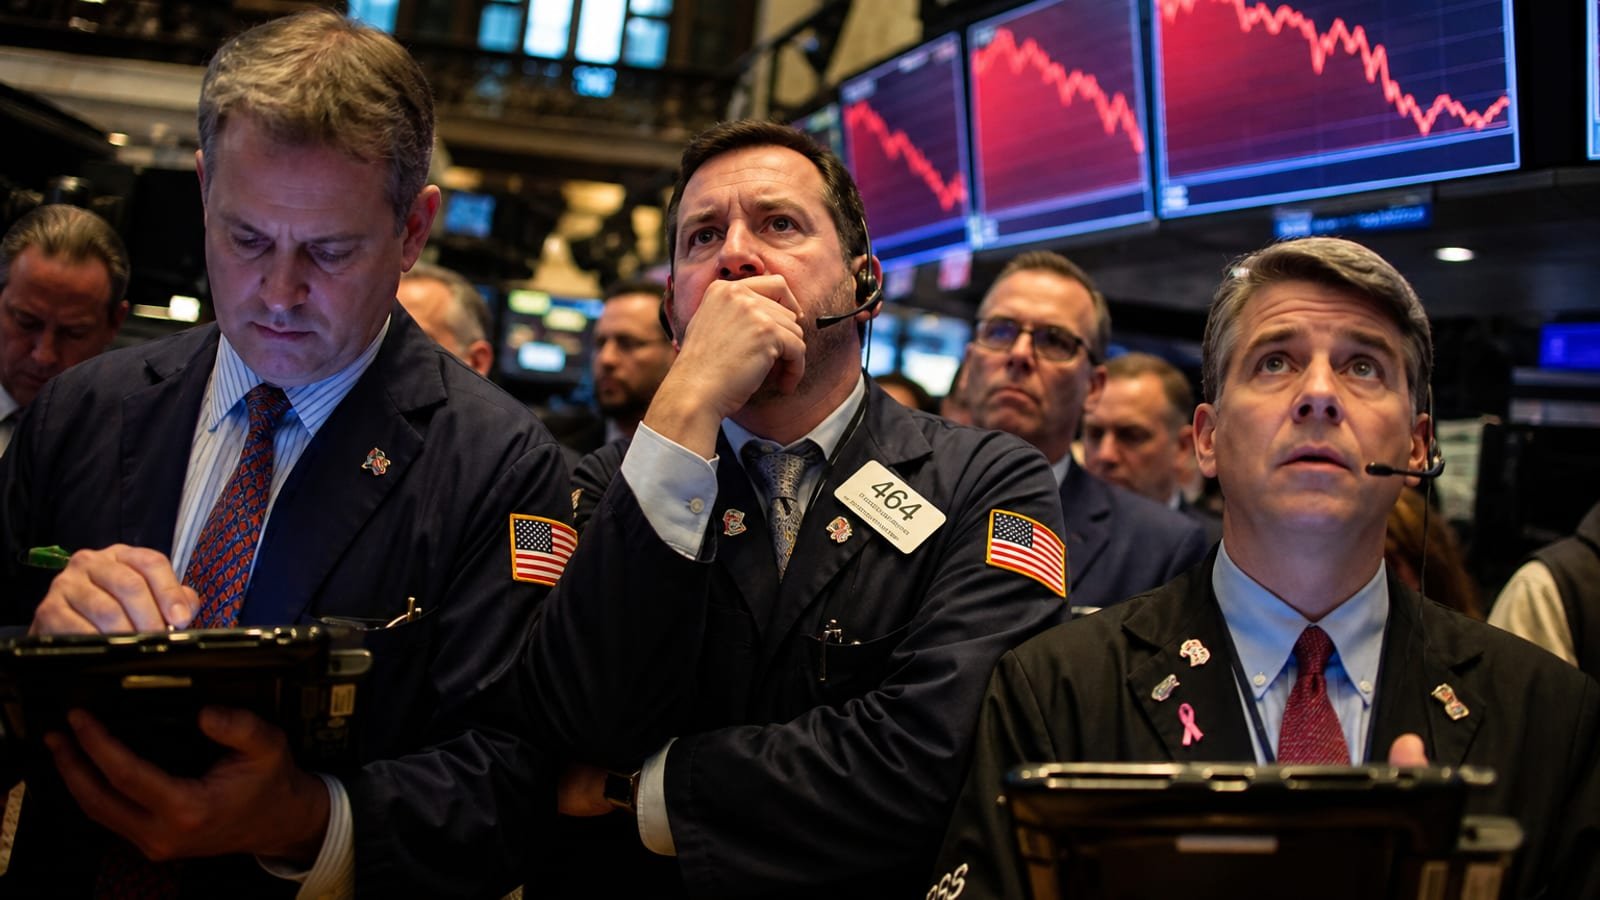
Investing.com, after the 4 p.m. ET bell Tuesday: Dow Jones 52,787.53, down 626.72, −1.17%. S&P 500 7,673.65, down 44.95, −0.58%. Nasdaq Composite 26,421.41, down 85.58, −0.32%. Decliners led on the NYSE 1,775 to 938. Nasdaq 2,181 to 1,261. That is a red first session after Labor Day, not a crash caption.
Oil did the work. October WTI $94.25, up $2.77, +3.03%. November Brent $99.33, up $2.33, +2.40%. The Houthi hits on southern Saudi energy sites this morning were already in the tape at 11:35. The close kept the $99 handle. USD/JPY 154.00. December gold $4,402.55, down 1.65%. VIX 15.73, up about 2.8%.
Intel closed +9.05% at $104.47 — the S&P’s top name, the midday Amazon-chip bid that survived the bell. HPE +7.78% to $56.05. Corning +7.56% to $165.96. Caterpillar +1.05% to $822.48 was the Dow’s green.
Healthcare and the old tape paid: Amgen −10.08% to $393.17. Stryker −8.81% to $276.43. Howmet −10.70% to $231.53. Salesforce −3.86%. Home Depot −2.29%. Bitcoin stayed under $80,000 and under $79,000 on the day. We will not invent a BTC settle.
PPI Thursday. CPI Friday. FOMC Sept. 15–16, Chair Kevin Warsh. Midday FedWatch was 58.4% for a hike. That is the week that grades the close.
What this means for you
If you hold an index, Tuesday was an oil tax. If you drive, the pump did not wait for the bell. If you needed 11:35 to be the story, it was a draft. This is the page. Not investment advice.
Bottom line: Dow 52,788. Brent $99.33. Intel ripped. Healthcare ate it. Thursday is PPI.
GLHR NEWS explains the news. Not investment, tax, or trading advice. Do your own work before you act.